Tax Resolution for IRS and California Tax Problems
Behind on filings, buried in penalties, or looking at a levy notice? Work directly with AJ Singh, CPA, EA, enrolled to practice before the IRS. We represent taxpayers before the IRS, FTB, EDD, and CDTFA. Flat fee, quoted before we start.
G&S Accountancy is a CPA firm in Rancho Cucamonga, CA. Our tax-resolution practice handles installment agreements, penalty abatement, levy and lien release, Offers in Compromise, unfiled returns, and audit representation for individuals and businesses across Southern California.
The short answer
Owe more than you can pay? There is a process for this.
If you owe the IRS or a California agency more than you can pay, you generally have four options: a payment plan (installment agreement), a payment plan sized to your real financials, Currently Not Collectible status, or an offer in compromise. Penalty abatement can shrink the balance under any of them.
All four start the same way: get every required return filed, get the financials right, and get ahead of the lien and the levy. The "Fresh Start Program" you hear advertised on the radio is the IRS's umbrella name for these same options. It is not a separate program you enroll in.
Profitable businesses end up here more often than people think, because the tax is charged on profit, not on cash in the bank. We explain how that happens, and what to do about it, in Profitable But Broke: What to Do When Your Business Owes the IRS.
Led by a named practitioner
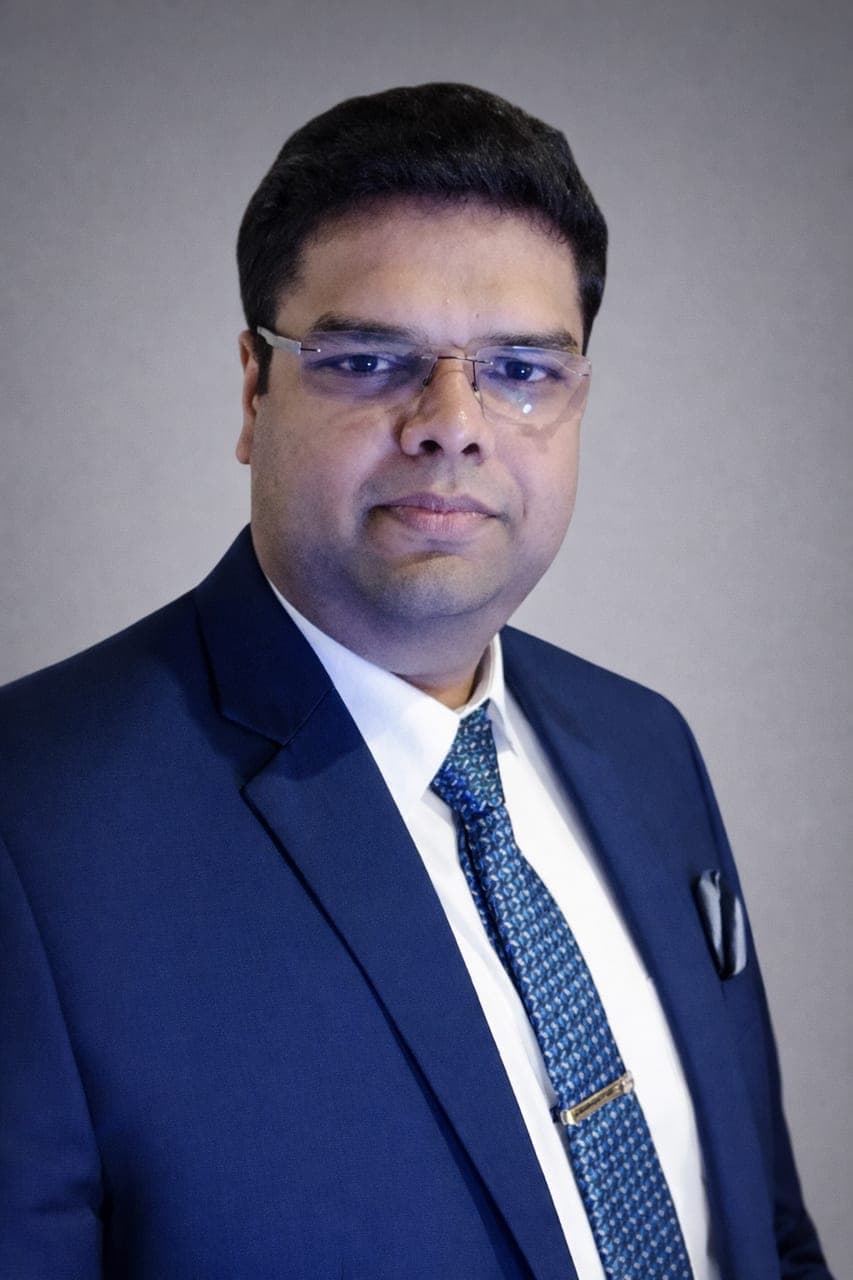
Your case is handled by AJ Singh, CPA, EA
Tax problems are personal, and you deserve to know exactly who is representing you. AJ Singh is the Managing Partner of G&S Accountancy and holds two of the most important credentials in tax controversy work: Certified Public Accountant (California) and Enrolled Agent. AJ Singh, CPA, EA, is enrolled to practice before the IRS and represents taxpayers at every administrative level of the IRS: audits, collections and appeals. That means G&S can handle every part of your case, from the first notice to the final resolution.
That matters. Many resolution outfits hand your file to a rotating call center. Here, a credentialed CPA and Enrolled Agent with 15+ years of experience owns the strategy, signs the filings, and negotiates directly with the IRS and California agencies on your behalf. Many of the business owners we represent are profitable but still can't pay the IRS, because tax is charged on profit, not on the cash in the bank.
- CPA (California) and Enrolled Agent
- Enrolled to practice before the IRS
- AICPA member with 15+ years in tax and audit representation
- Bilingual team support in English and Spanish
Federal and California representation
Which letter is on your kitchen table?
California taxpayers rarely deal with just one agency. Every notice below has a deadline printed on it, and what you do before that date matters more than the last three years. Send us the letter, even the ones you have not opened.
IRS
Balance-due notices usually arrive in order: CP14 (first bill), CP501 and CP503 (reminders), then CP504 (intent to levy certain assets, such as a state refund). The one that must never be filed away is the Final Notice of Intent to Levy (LT11 or Letter 1058), which starts a 30-day window to request a Collection Due Process hearing.
FTB
Franchise Tax Board notices cover unpaid California income tax, estimated penalties, and unfiled returns. FTB collects with bank levies and Earnings Withholding Orders (wage garnishments), and it can suspend a corporation or LLC that does not file or pay, which stops the entity from doing business in California.
EDD
Employment Development Department notices usually follow a payroll audit or a worker-classification question. A Notice of Assessment has a short window to file a petition for reassessment.
EDD audit defense → about EDDCDTFA
Sales-and-use-tax, IFTA, and other fee-program audits and assessments.
CDTFA audit defense → about CDTFAYour real options for IRS and California tax debt
There is no secret program and no enrollment. There is your data, the agency's formulas, and the paperwork done right. These are the tools, in roughly the order we reach for them.
Installment Agreements
Individuals who owe $50,000 or less in combined tax, penalties, and interest can usually get an IRS payment plan of up to 72 months without full financial disclosure. Above that, or when the standard payment would sink the business, the plan is built on your financial statement (Form 433-A for individuals, Form 433-B for businesses), so the payment matches what your numbers can actually support. FTB has its own installment agreements. Payroll tax balances have their own rules; we handle those case by case.
Currently Not Collectible
If the numbers show nothing is left after reasonable living and business expenses, the IRS can mark the account Currently Not Collectible and pause levies and garnishments. The debt does not go away and interest keeps running, but the 10-year collection clock keeps running too, and the IRS revisits your finances periodically.
Offer in Compromise
Settling for less than you owe is real, but it is formula based: the equity in your assets plus a set number of months of future disposable income. We run that math first. When it works, we file. When it does not, we tell you straight, because a rejected offer costs you the fee and months of time.
Penalty Abatement
First-time abatement removes failure-to-file, failure-to-pay, and failure-to-deposit penalties for one tax year if you had no penalties in the prior three years and are current on filing. It is the most underused relief there is, and we always ask for it. If it does not apply, we pursue reasonable-cause relief in writing. Removing a penalty also removes the interest charged on it.
Liens & Levies
A lien is a claim on what you own; a levy actually takes it (a bank account, wages, receivables). We move to stop a levy, request a release where the facts support it, and use lien withdrawal, subordination, or discharge when a refinance or a sale depends on it.
Unfiled & Back Returns
Nothing gets negotiated with returns missing. The IRS generally wants the last six years filed. We reconstruct the records, file accurate returns, and replace any Substitute for Return the IRS prepared, which almost always overstates what you owe.
What this looks like in real life
A $40,000 balance, and the 30 days that matter
Let's take an example. A small business owner skipped two years of estimated payments because the cash was not there. The returns were filed, the balance grew, penalties stacked on top, and now there is a $40,000 bill and a letter giving about 30 days to respond.
The first call is not to the IRS. It is to get a power of attorney (Form 2848) signed, so the IRS talks to us, not you. We pull the transcripts, so we work from the IRS's own records rather than the letters, and we find surprises constantly: an old payroll form never filed, a payment applied to the wrong year, sometimes a balance that is wrong in your favor.
On a $40,000 balance, a streamlined plan over 72 months comes to roughly $600 a month, and the business keeps running. If a first-time abatement takes the penalty off one of those years, the balance, and the payment, gets smaller before we ever sign anything.
The same squeeze happens to profitable businesses carrying equipment loans. We walk through that case, with the numbers, in Profitable But Broke.
Liens and levies
A lien is a warning. A levy is the money leaving.
A Notice of Federal Tax Lien is a public claim against everything you own. It does not show up on your credit report (tax liens came off all three consumer credit reports in 2018), but it is a public record your mortgage lender, your equipment finance company, and your factoring company can find.
A levy is different: it actually takes the money. A bank levy freezes what is in the account on the day it arrives, and the bank holds those funds for 21 days before sending them, which is the window to get it released. A wage levy keeps taking a share of every paycheck until it is released.
Before the IRS can levy most property, it must send a Final Notice of Intent to Levy and your right to a Collection Due Process hearing. That 30-day window is the most valuable deadline in the whole process: a timely hearing request generally holds the levy while the case is heard. California agencies follow their own notice rules, and FTB can levy and garnish on its own authority.
The whole game is timing. Every option on this page is easier before a lien is filed, before a levy hits the account, and before a defaulted plan is on the record.
- "Notice of Intent to Levy" in the heading: call us the same day
- A bank levy: 21 days to act before the funds are sent
- A lien blocking a refinance or sale: ask about subordination or discharge
What nobody advertises
The honest downsides of a payment plan
A payment plan is relief, but the debt is still there. You should know these four things before you sign anything.
- Interest does not stop. The IRS rate resets every quarter, and the late-payment penalty keeps adding too (smaller on a plan, but not zero).
- Plans have rules. Miss a payment or fall behind on a new tax year, and the agreement can default.
- Refunds get kept. While you owe, the IRS applies refunds to the balance.
- A plan is temporary by design. When the good years come back, we pay the balance down early rather than riding out 72 months of interest.
How tax resolution works with G&S
A clear process replaces the uncertainty of dealing with a tax agency on your own. The fee is flat, and we quote it before we start work.
Free case review
We look at every notice, tell you honestly where you stand, and what realistic outcomes look like. No obligation.
Power of attorney & transcripts
You sign Form 2848 (and the California equivalents), the agencies talk to us, and we pull your records so we work from facts.
Compliance check & collection hold
We go through every year, every form, every balance with the agency, and ask for a hold on collections while the record is fixed.
Catch-up filings
Any unfiled returns get prepared and filed, replacing substitute returns that overstate what you owe.
Resolve
We build the financial statement from real workpapers, request penalty abatement, and negotiate the right option: installment agreement, Currently Not Collectible, or an offer in compromise.
Stay resolved
We keep you current on estimated payments and deadlines so the agreement holds and the problem does not come back.
What clients say
Clients trust us with tough tax problems
“Very responsive especially, Lorena. She helped me numerous times navigating tough tax resolutions with IRS and FTB in a timely manner. She is the problem solver!!”
“I have been with this company for quite some time now, about 10 years, and the staff is amazing. They respond quickly and won’t stop reaching out until the job is done.”
“Quality service, always on time. Lorena Contreras atiende y explica muy bien en Español.”
“Very proactive and will consistently check up with you to ensure everything goes smoothly.”
Related reading
More on resolving IRS and California tax debt
Penalties, liens, levies and the programs that resolve them, explained.
- Profitable But Broke: What to Do When Your Business Owes the IRSWhy a profitable business can still owe tax it cannot pay, and the four real options.Read the article
- We Read Trucking Tax Debt Differently: How a Trucking Company Gets the IRS to Slow Down — or StopA trucking company that owes the IRS has two real options: Currently Not Collectible status or an installment agreement built around actual cash flow.Read the article
- Unfiled Tax Returns? Start With the Facts, Not a GuessStart with IRS records and your business facts. Understand the limits of the six-year policy, substitute returns and refund deadlines before choosing a filing plan.Read the article
- Avoid Costly IRS Penalties: Qualify for First-Time Penalty Abatement TodayPaying taxes is a crucial responsibility that all citizens must fulfill. However, sometimes taxpayers may be unable to…Read the article
- Settling Old Balances with the FTB: How to Pay Your Dues and Avoid PenaltiesOwing old balances to the Franchise Tax Board (FTB) can be a stressful experience. Whether it’s due to a failure to file…Read the article
- Avoid a Tax Audit: How to Keep Your Tax Returns Off the IRS Audit RadarAs the tax season begins, the last thing you, as a taxpayer, want is an IRS (Internal Revenue Service) audit. The…Read the article
- Avoid IRS Penalties: Act Now to Correct and Update Your ERC ClaimsIn the evolving Employee Retention Credit (ERC) landscape, proactive compliance is crucial. G&S Accountancy (GNS)…Read the article
- Disaster Tax Relief Explained: What You Need to Know After the LA WildfiresDisaster Tax Relief: Your Guide to Minimizing Penalties and Interest After a Catastrophe If you’re dealing with the…Read the article
- FTB Estimated Tax PaymentsFTB Estimated Tax Payments: What, Why, and How for California Business Entities Running a business in California comes…Read the article
Tax Resolution FAQ
Answers before you owe another day of interest
Common questions about resolving IRS and California tax problems. Have a situation that is not covered here? Ask us in a free case review.
Get a Free Case Review →A CPA is a state-licensed accountant; an Enrolled Agent (EA) is enrolled to practice before the IRS. AJ Singh holds both: AJ Singh, CPA, EA, enrolled to practice before the IRS. That combination means one person can both defend the numbers and argue the case.
No. Unfiled returns are one of the most common situations we handle. We reconstruct your records, prepare accurate returns, and file them in the right order. In many cases the IRS filed a substitute return that overstates what you owe, and filing an accurate return actually reduces the balance before we negotiate the rest.
Sometimes an offer settles a balance for far less than you owe, but only when the math says you genuinely cannot pay more: the equity in your assets plus a set amount of future income. We run that calculation first and tell you honestly whether an offer is realistic. If it is not, we pursue what is, such as a payment plan built on your financials or Currently Not Collectible status.
Levies and garnishments are time-sensitive, so contact us as soon as you get the notice. Once we are your authorized representative we can often move quickly to request a release or hold while we get you into compliance and negotiate a resolution. The sooner we start, the more options you have.
Often, yes. We pursue first-time penalty abatement if you have a clean prior history, and reasonable-cause relief when circumstances (illness, disaster, reliance on bad advice) justify it. Removing penalties also removes the interest that accrued on those penalties.
Yes and no. Fresh Start is the IRS's umbrella name for expanded payment plans, lien thresholds, and offer-in-compromise rules, not a program you enroll in. Anyone selling "Fresh Start enrollment" is filing the same forms any qualified CPA or Enrolled Agent files.
It means the agency has reviewed your financials, agreed you cannot pay right now, and paused collection, so no levies or garnishments. The debt remains, interest still accrues, and your finances are reviewed again periodically.
Yes, for individuals. The FTB offers one-time penalty abatement for tax years beginning on or after January 1, 2022, if your recent filing history is clean. Business entities and earlier years need a reasonable-cause request instead, which we prepare in writing.
Yes. Our team includes bilingual staff, and clients specifically note that Lorena Contreras explains resolution matters clearly in Spanish. Podemos ayudarle en español.
We are based at 8300 Utica Ave, Suite 283, Rancho Cucamonga, CA 91730, and serve individuals and businesses across the Inland Empire and Southern California. Your case is led by AJ Singh, CPA, EA, and supported by our tax-resolution team.
Stop the notices. Start the resolution.
Bring the letters, even the ones you have not opened. We will pull your records, run the full compliance check, and tell you exactly where you stand. Flat fee, quoted before we start.